The U.S. housing market has spent the last several years defying expectations. While many anticipated higher interest rates would dramatically slow borrowing activity, a different trend has emerged. Instead of selling their homes, millions of homeowners have chosen to stay exactly where they are.
The reason is simple. Homeowners who secured historically low mortgage rates during the past decade are understandably reluctant to exchange those loans for today’s borrowing costs. Even when a family outgrows its home, wants additional space, or needs significant repairs, moving often makes less financial sense than improving the property they already own. That dynamic is creating a unique opportunity for lenders, investors, and servicing organizations. As homeowners seek ways to access capital without refinancing their primary mortgage, home equity products are gaining renewed attention. At the same time, personal loans continue to provide funding for everything from debt consolidation and medical expenses to home improvements and everyday financial needs. Together, these trends may represent one of the most significant growth opportunities in consumer finance over the next several years.
The Rise of the “Stay-and-Improve” Homeowner
Historically, homeowners often addressed changing needs by moving. A growing family could purchase a larger home, a homeowner wanting a modern kitchen might roll renovation costs into a new mortgage, and someone seeking a different location would simply enter the housing market as both a seller and buyer.
Today’s market is different. For many homeowners, a move means giving up a mortgage rate that may be several percentage points lower than current financing options. In many parts of the country, that difference can significantly increase a monthly housing payment, even when purchasing a similarly priced home. As a result, many homeowners are choosing to remain in place and invest in their existing properties instead.
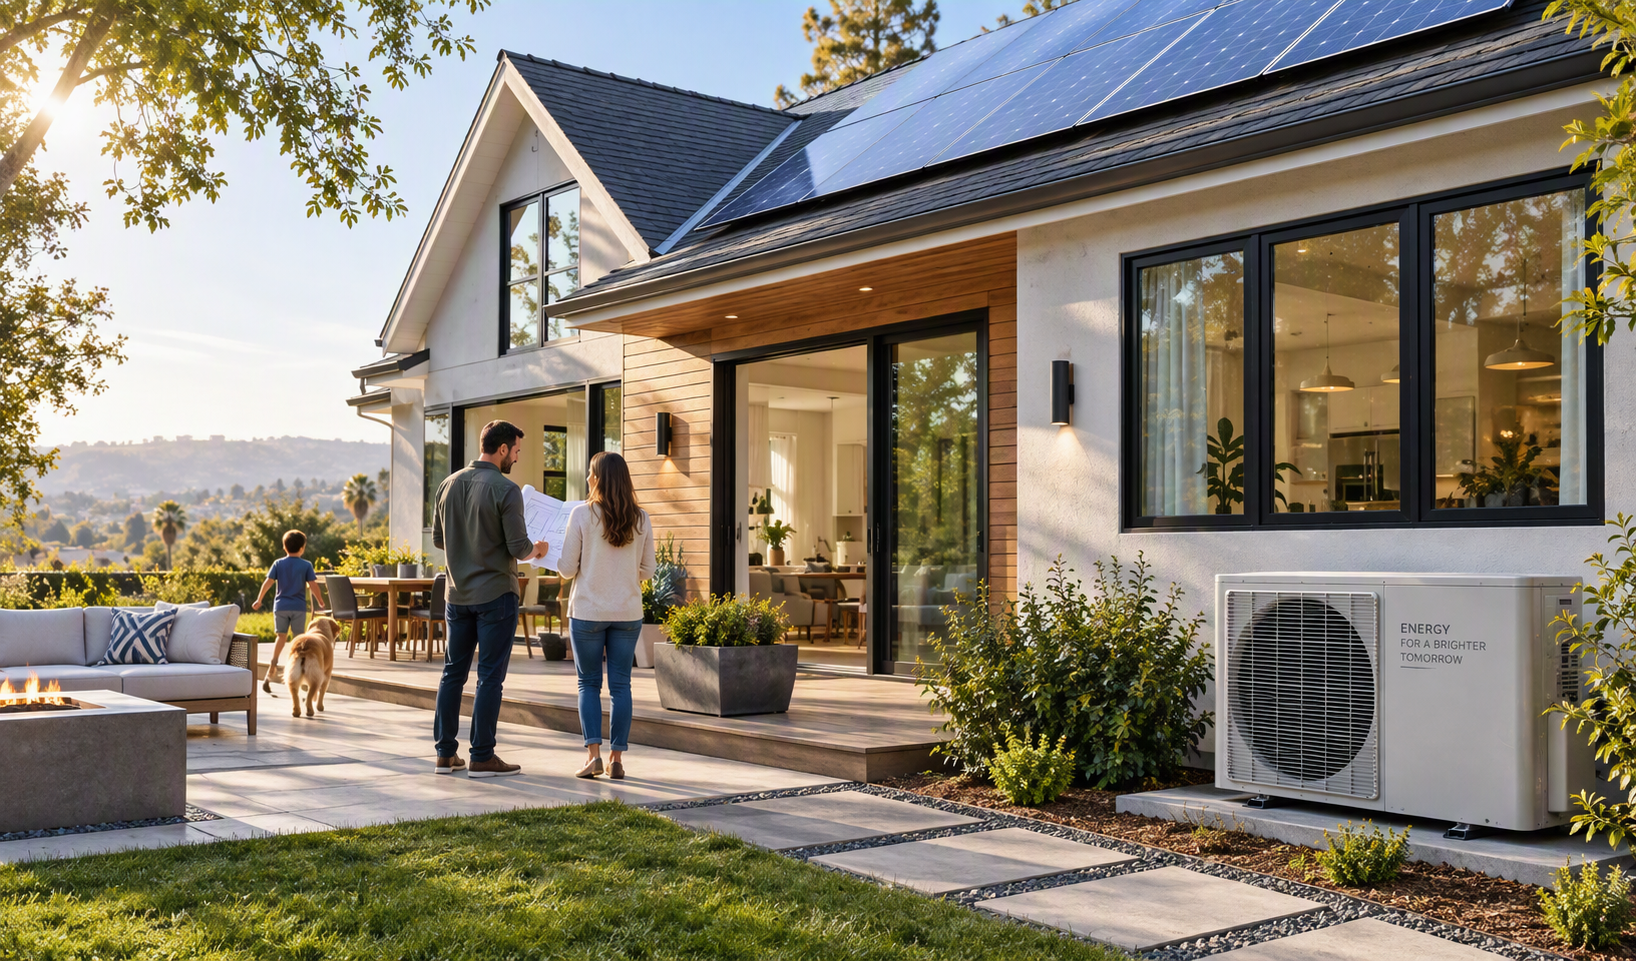
That decision drives demand for financing options that allow homeowners to tap accumulated equity without disturbing their first mortgage. Home renovations, additions, roof replacements, HVAC upgrades, and other major projects all require access to capital. Home equity products are often positioned to meet that need.
Energy efficiency projects represent another important component of this financing need. Homeowners looking to reduce energy consumption, improve comfort, or modernize aging properties may invest in projects such as energy-efficient HVAC systems, windows, heat pumps, insulation, solar installations, and other upgrades. Because these improvements can require a meaningful upfront investment, financing can play an important role in making them more accessible. For lenders and financing providers, the continued interest in energy efficiency also creates opportunities to support homeowners investing in the long-term performance of their properties.
The trend extends beyond discretionary improvements. Weather-related events, aging homes, and insurance limitations can create unexpected expenses that must be addressed regardless of market conditions. In many cases, homeowners need financing solutions that bridge the gap between available insurance proceeds and actual repair costs. The result is a lending environment where home equity products may become increasingly important to both borrowers and lenders.
A Market Larger and More Diverse Than Many Realize
The home equity market is often associated with large national banks. While those institutions remain major participants, the market itself is much broader and more fragmented. Credit unions, regional banks, community financial institutions, specialty finance companies, and fintech lenders all play important roles in originating home equity products. The competitive market continues to evolve as technology-driven lenders look for new ways to reach consumers and streamline the borrowing experience. Unlike some lending categories that are controlled by a relatively small number of dominant participants, home equity lending includes a wide range of organizations with different business models, target markets, and growth strategies. That fragmentation creates room for emerging lenders and fintech platforms to establish meaningful positions within the market and creates opportunities for innovation and expansion.
Why Fintech Lenders Are Paying Attention
Many of today’s fastest-growing lending organizations built their reputations on origination. Their competitive advantage often stems from digital customer experiences, streamlined application processes, alternative underwriting capabilities, and highly efficient marketing channels that allow them to acquire borrowers quickly and compete effectively against larger institutions.
But growth creates its own challenges. As loan portfolios expand, lenders must manage customer service, payment processing, compliance oversight, reporting requirements, delinquency management, and portfolio administration. What begins as a technology challenge gradually becomes an operational one.
This evolution is not unique to any single company. It is part of a broader maturation process that many growing lenders eventually experience. The organizations that excel at acquiring customers are not always the organizations best positioned to build large servicing operations from scratch. As portfolios grow, management teams increasingly evaluate which functions represent core competitive advantages and which may be better supported through strategic partnerships.
From Vendor Relationships to Growth Partnerships
The most successful partnerships in financial services rarely begin with discussions about servicing logistics. They begin with growth. Lenders want partners who can help them scale efficiently, improve their customers’ experiences, support compliance obligations, and create operational flexibility. They are looking for organizations that can strengthen their business rather than simply perform a transactional function.
This is particularly relevant in the home equity and personal lending markets. As lenders enter new asset classes, launch products, acquire portfolios, or pursue acquisitions, operational demands increase. Servicing infrastructure, compliance programs, borrower communication strategies, collections capabilities, and portfolio administration become increasingly important to long-term success.
Organizations that can support the entire loan lifecycle often provide additional value because they reduce complexity. Rather than coordinating multiple vendors across various functions, lenders can focus internal resources on product development, borrower experience, investor relationships, and growth initiatives.
Personal Loans Tell a Similar Story
While home equity lending receives significant attention, many of the same dynamics are visible within the personal loan market. Consumer demand for personal financing remains strong. Borrowers continue to seek solutions for debt consolidation, medical expenses, home projects, and other financial needs. As economic conditions change, many consumers use personal loans to simplify or restructure existing obligations. For lenders, this creates attractive opportunities for portfolio growth. Yet the same operational realities apply. Larger portfolios require stronger servicing capabilities, enhanced compliance oversight, more sophisticated analytics, and effective borrower engagement strategies. Growth and servicing remain interconnected.
The Opportunity Ahead
The most interesting aspect of today’s lending environment may not be the technologies being developed or the products being launched. It may be the convergence of borrower demand, market fragmentation, and operational necessity.
Homeowners are remaining in place and seeking new ways to access capital. Personal lending continues to address a wide range of financial needs. Fintech lenders are expanding into new asset classes and pursuing growth opportunities that were once dominated by traditional institutions. At the same time, successful growth increasingly depends on what happens after a loan is originated.
The next generation of lending leaders will not be defined solely by their ability to attract borrowers. They will also be defined by their ability to scale operations, navigate compliance requirements, manage portfolio performance, and deliver consistent borrower experiences throughout the life of the loan.
One of the most common misconceptions in lending is that value creation ends when a loan is funded. In reality, origination marks the beginning of a long-term relationship between lender and borrower. The borrower experience, portfolio performance, compliance outcomes, and operational efficiency that follow can have just as much impact on long-term success as the initial lending decision itself.
As lenders grow, the focus naturally expands beyond customer acquisition and loan funding. Supporting borrowers throughout the life of the loan, identifying potential challenges early, and maintaining consistent servicing operations can strengthen customer relationships while helping improve portfolio performance. In that sense, servicing is not simply a back-office function. It is a critical component of the overall borrower experience and an important contributor to sustainable growth.
For lenders navigating the evolving home equity and personal loan markets, growth is still the objective. The difference is that sustainable growth increasingly requires the right operational foundation behind it. Origination opens the door, but long-term success depends on everything that follows.
Goal has consistently partnered with clients, offering expertise, guidance, and crucial services that lead to seamless and prosperous transactions. Specializing in ABS investor reports, financial statements, and associated reporting services, we are recognized leaders in the structured finance sector. Our comprehensive suite of solutions goes beyond standard reporting, encompassing vital services such as loan servicing, backup servicing, default prevention, collections, rating agency support, and master servicing. With a steadfast commitment to excellence, we facilitate a wide array of ABS transactions across diverse asset classes, ensuring our clients receive unparalleled support throughout their financial journey. Contact us to discover how we’ve enabled hundreds of clients to successfully tap into the securitization markets; we’ve proudly assisted in four inaugural client securitizations in 2024 alone. We’re eager to discuss your specific questions and objectives, and to tailor a solution that best meets your unique business requirements
To learn more about Goal Solutions and schedule an exploratory call, please visit: https://goalsolutions.com/ or contact:
Brian Cox
Vice President – Business Development
617-680-3515
[email protected]